Skip to content
United States editionIn your inbox within a minute30-day money-back promise
The End of Life Plannerby Valoren

General information · not a substitute for the advice of an attorney.

Free · general informationUnited States

Taxes after a death

The returns the IRS describes after a death, and when it says each is due, in its own words. Nothing on this page says which of them a particular estate owes; that is for the IRS, or a tax professional, to say.

  • Every fact dated, in the official words
  • Each state’s own law

Every quotation checked November 10, 2026How we check

The free first-week checklist

Pages taken from the planner, by email: who to phone first, and a blank records sheet.

We use your email address to send the checklist and those emails, and for nothing else. We do not sell it. We first send one email asking you to confirm your address. Privacy notice

The phone page, free

One sheet: where the passcode is kept, your Apple Legacy Contact, and the recovery codes. It is the planner’s first section, cut short.

Download the phone page (PDF) →

Every quotation on this page is the official body’s own words, as they stood on the day we read them. The date is beside each one.

The final income tax return, and claiming a refund

In general, file and prepare the final individual income tax return of a deceased person the same way you would if the person were alive. Report all income up to the date of death and claim all eligible credits and deductions.

Internal Revenue Service · general information · checked November 10, 2026

Use Form 1310 to claim a refund on behalf of a deceased taxpayer.

Internal Revenue Service · general information · checked November 10, 2026

A final return for a decedent who was a calendar year taxpayer is generally due on April 15 following the year of death, regardless of when during that year death occurred.

Internal Revenue Service · general information · checked November 10, 2026
The estate’s own income, and its return

When someone dies, their assets become property of their estate. Any income the assets generate become part of the estate and may require you to file an estate income tax return.

For calendar year estates and trusts, file Form 1041 and Schedule(s) K-1 on or before April 15 of the following year.

Internal Revenue Service · general information · checked November 10, 2026

The estate tax return: when one is required, and when it is due

Most relatively simple estates (cash, publicly traded securities, small amounts of other easily valued assets, and no special deductions or elections, or jointly held property) do not require the filing of an estate tax return.

A filing is required if the gross estate of the decedent, increased by the decedent’s adjusted taxable gifts and specific gift tax exemption, is valued at more than the filing threshold for the year of the decedent’s death (part of a longer sentence)

Internal Revenue Service · general information · checked November 10, 2026

The Working Families Tax Cuts Bill (WFTC) was signed into law on July 4, 2025 as Public Law 119-21. WFTC amends § 2010(c)(3) by increasing the basic exclusion amount to $15,000,000 for calendar year 2026.

Internal Revenue Service · general information · checked November 10, 2026

If Form 706 is required, the return and payment of any tax is due within 9 months after the date of the decedent’s death.

Internal Revenue Service · general information · checked November 10, 2026

Friends sharing breakfast at a sunny patio table among citrus trees
Friends on a desert patio at sunset, with a saguaro in the distance
An older couple on a porch swing under a flag, mugs in hand, a neighbor raking leaves below
FAQ

Common questions

In general, file and prepare the final individual income tax return of a deceased person the same way you would if the person were alive. Report all income up to the date of death and claim all eligible credits and deductions.

Internal Revenue Service · general information · checked November 10, 2026

Use Form 1310 to claim a refund on behalf of a deceased taxpayer.

Internal Revenue Service · general information · checked November 10, 2026

A final return for a decedent who was a calendar year taxpayer is generally due on April 15 following the year of death, regardless of when during that year death occurred.

Internal Revenue Service · general information · checked November 10, 2026
When someone dies, their assets become property of their estate. Any income the assets generate become part of the estate and may require you to file an estate income tax return.

For calendar year estates and trusts, file Form 1041 and Schedule(s) K-1 on or before April 15 of the following year.

Internal Revenue Service · general information · checked November 10, 2026
Most relatively simple estates (cash, publicly traded securities, small amounts of other easily valued assets, and no special deductions or elections, or jointly held property) do not require the filing of an estate tax return.

A filing is required if the gross estate of the decedent, increased by the decedent’s adjusted taxable gifts and specific gift tax exemption, is valued at more than the filing threshold for the year of the decedent’s death (part of a longer sentence)

Internal Revenue Service · general information · checked November 10, 2026
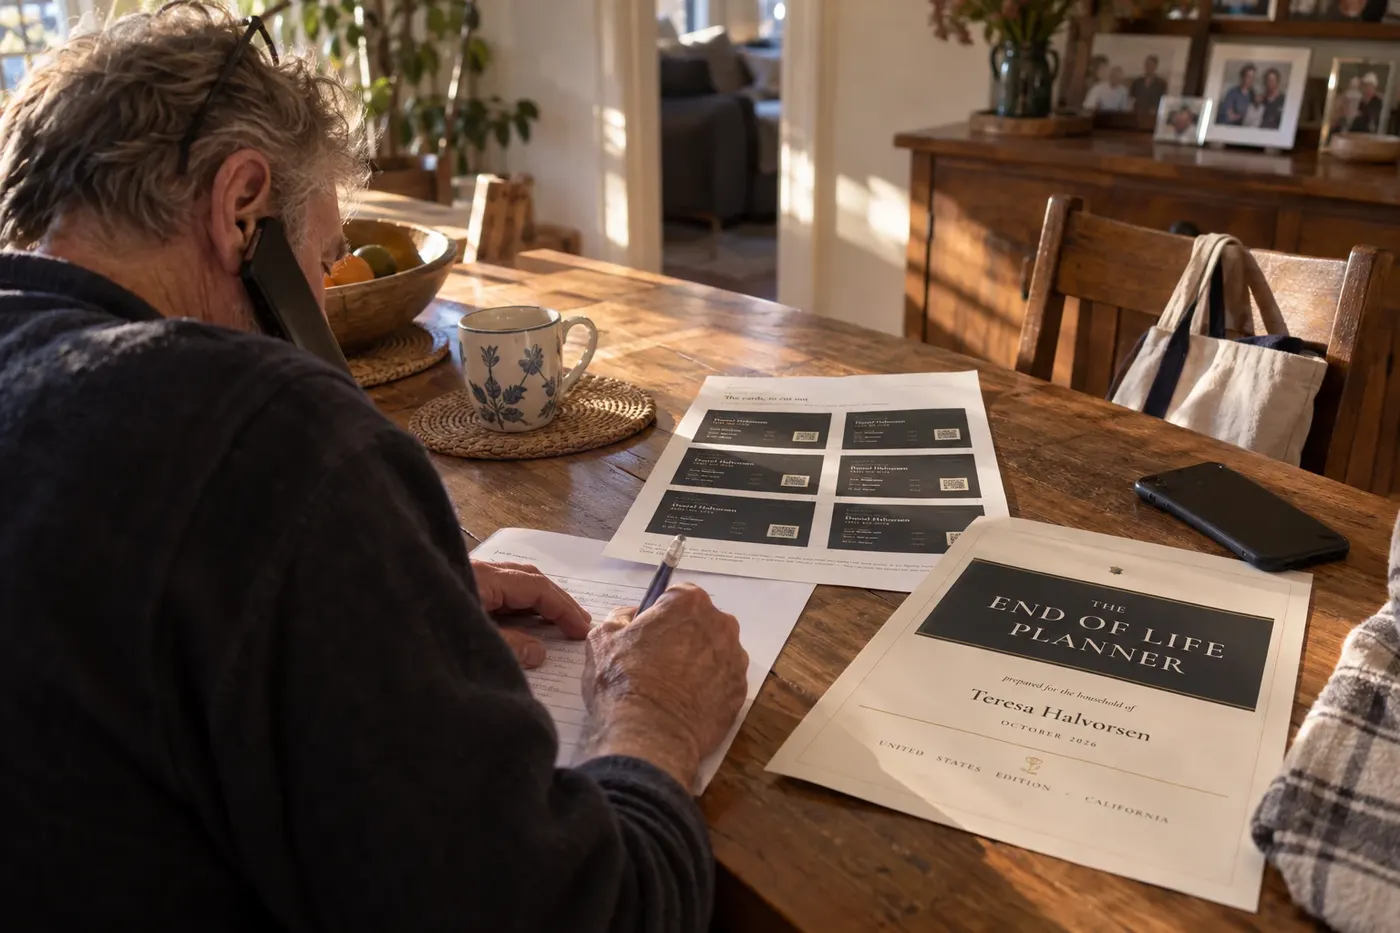
For anyone who would rather their family found it all in one place than went looking.

A couple. A parent. An adult child and a parent, doing it together. One sitting starts it; keep it current, and tell someone where it is.

“Apple can’t help remove the passcode lock without erasing the device.”

Apple says so on the page where families send it the death certificate. The first section of the planner is the one that stops that: the passcode, the Legacy Contact and the recovery codes, written down while you still can.

Apple Support, “Request access to a deceased family member’s Apple Account” · read November 2, 2026
A man on the telephone with the planner's pages open on the table